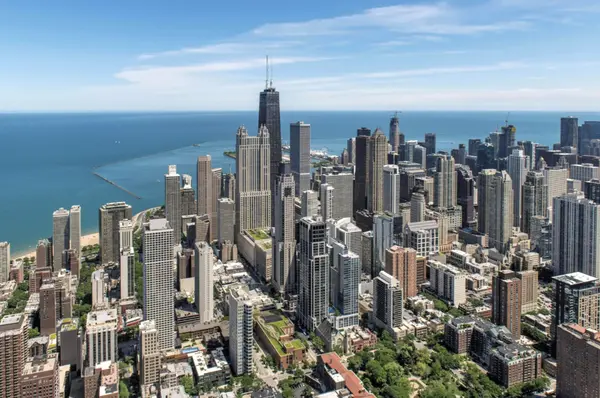
Near North Chicago Market Report Q1 2026: River North, Gold Coast & Streeterville Trends
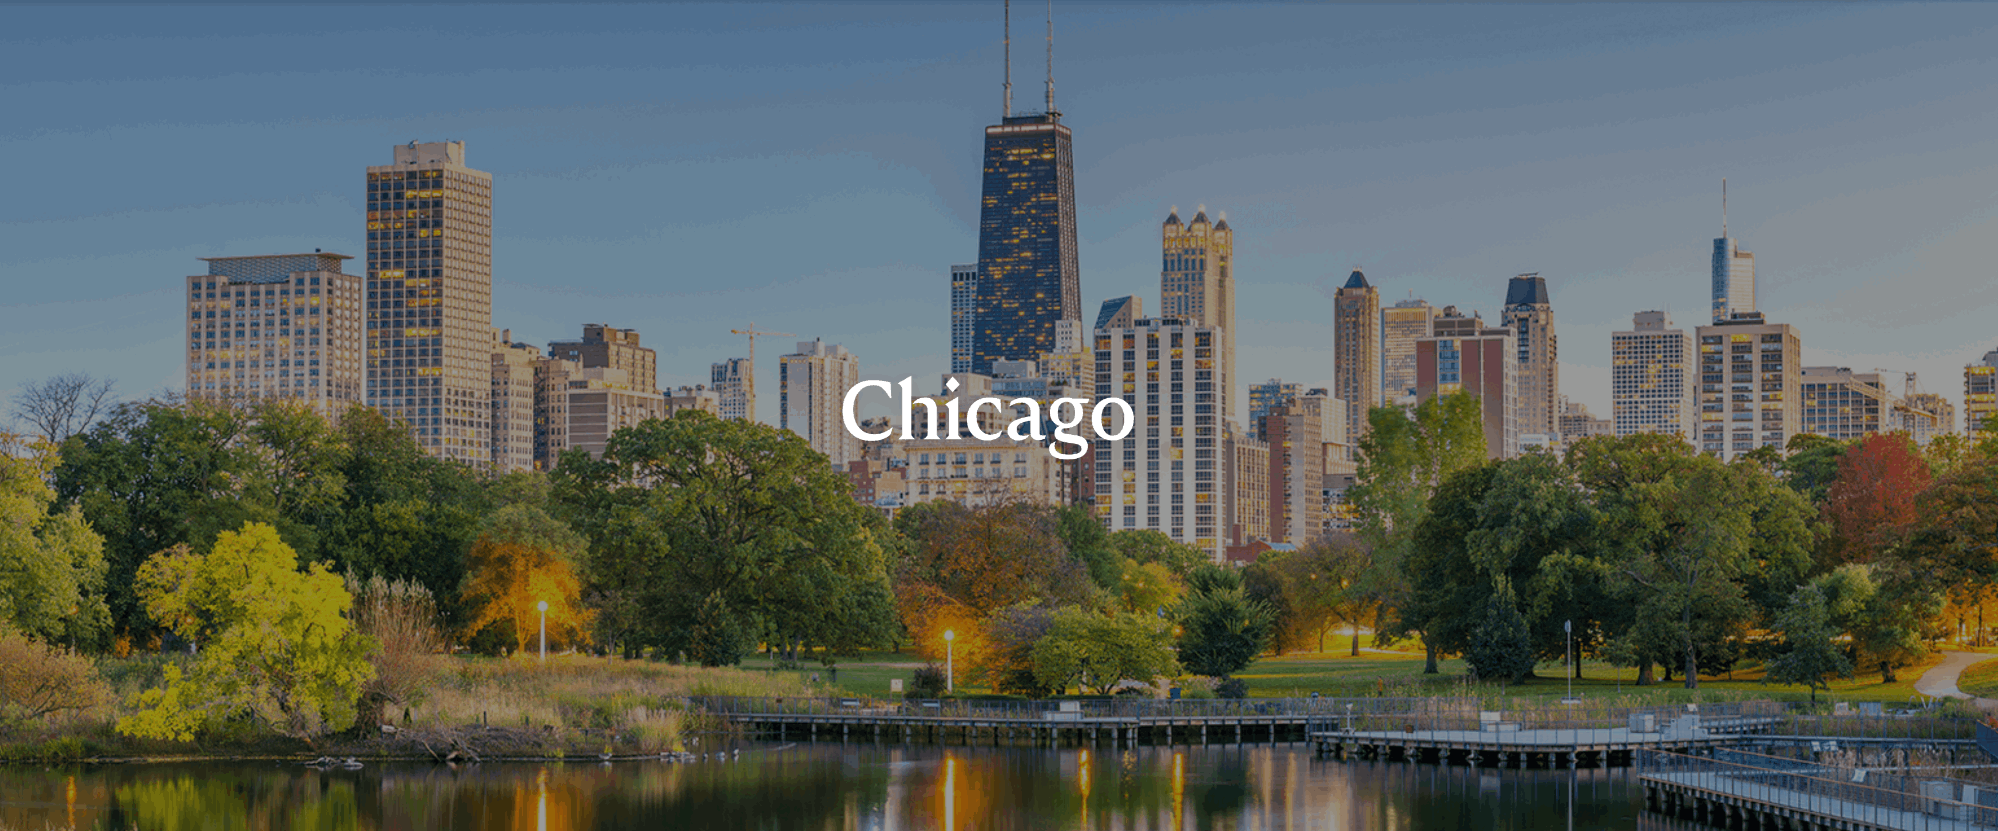
Chicago Near North Q1 2026: Buyers Are Changing the Rules
River North | Gold Coast | Streeterville
Word Count: ~850–950 words • Estimated Read Time: 3–4 minutes
The Near North real estate market moved through the first quarter of 2026 with a familiar structure but a more defined buyer mindset. In January, we published a story on Why River North, Streeterville & the Gold Coast Are Back in Buy Territory. Now, at the end of the first quarter of 2026, we are seeing it bear out in activity and volume.
Condominiums continue to carry the market by a wide margin. Nearly 200 units closed in Q1, generating just over $211 million in volume, with another $224 million currently under contract. Inventory remains elevated at just over 300 active listings, which continues to give buyers choice and leverage.
The most consistent segment, both in terms of closed sales and pending activity, sits between $1 million and $2 million. That range produced the highest number of transactions on both sides of the ledger, reinforcing its position as the core of the Near North luxury condo market.
Below that, the $500,000 to $800,000 range continues to provide the market’s depth. These units account for a steady share of transactions and reflect the broader base of buyers still active in the city—those trading up, re-entering, or maintaining a foothold in the urban core.
Above $2 million, activity remains present but selective. Units are trading, but with longer timelines and more scrutiny. The data shows a clear increase in days on market as pricing moves beyond $3 million, reinforcing what most sellers at that level already understand: pricing discipline is not optional in today’s environment.
The single-family segment tells a different story.
Only five homes closed during the quarter, with a total volume of just under $20 million. Another eleven properties are under contract, representing about $28 million in pending volume, while thirteen homes remain on the market with a combined value exceeding $65 million.
What stands out is not just the scale, but the distribution. Closed sales were concentrated above $2 million, including activity at the $5 million level, while current contract activity is strongest between $1 million and $2 million. That suggests a market that is still functioning—but with a narrower buyer pool and a longer decision cycle.
Inventory in this segment remains top-heavy, particularly above $5 million, where days on market stretch significantly. It is, and has been, a prestige segment—one where the right property will sell, but not quickly, and rarely without adjustment.
Taken together, the Near North continues to operate as a two-track market. Condominiums provide liquidity and volume. Single-family homes represent scarcity, but not necessarily speed.
So what has changed?
What has changed—and this is where the first quarter begins to separate itself from prior years—is the buyer.
Price no longer defines value. Total cost of ownership does.
Buyers are more informed than they have been in years. Not just on pricing, but on the full cost of ownership. The conversation has shifted from “what is the asking price” to “what does it actually cost to live here.”
That shift is most clearly showing up in two places.
The first is HOA assessments.
Buyers are no longer looking at the monthly number in isolation. They are breaking it down—often to a price per square foot for both the unit and the assessment—and evaluating what that number delivers. Buildings that provide a true level of service, staffing, and amenities are still finding their audience. In many cases, those buildings are outperforming.
But where the fee feels disconnected from the experience, resistance is immediate. High assessments without a clear value proposition have become one of the fastest ways to stall a deal.
The second is property taxes.
Taxes have always been part of the equation in Chicago. What’s different now is where they sit in the decision process. They are no longer a secondary consideration—they are often one of the first.
Buyers are underwriting the total cost of ownership in a much more disciplined way. That includes comparing tax burdens across neighborhoods, factoring long-term exposure, and weighing those costs directly against purchase price and perceived value.
Preparing to buy or sell?
In practical terms, this means that pricing alone is no longer enough to position a property correctly. The combination of price, taxes, and assessments now defines the opportunity—or eliminates it.
That’s where the market stands as we move into the second quarter.
There is activity. There is demand. But there is also a level of clarity from buyers that wasn’t as pronounced even a year ago.
And that clarity is shaping outcomes.
Read our latest blog stories on:
HOA Assessment Fees in Chicago
The Real Cost of Closing. Chicago 2026
— Craig Hogan & Rudy Zavala
Hogan Zavala Group | Engel & Völkers Chicago
FOLLOW OUR YOUTUBE CHANNEL HERE
Details on the top 10 markets in Chicago are just a click away!
Categories
- All Blogs (130)
- Adaptive Reuse (2)
- Architecturally Significant (23)
- Architecture (59)
- Art (2)
- Art Collecting (2)
- Bespoke Lighting (2)
- Buena Park (1)
- buyer strategy (30)
- Career Moves (9)
- chandeliers, (1)
- Chicago HOA Fees (7)
- Chicago Luxury Real Estate (94)
- Chicago Property Taxes (4)
- closet design (2)
- Co-Ownership (3)
- Coffee (1)
- Condo Assessments (7)
- coop apartments (5)
- cooperative apartments (8)
- custom closet advice (1)
- Days on Market (16)
- Design (51)
- Fulton Market District (8)
- Gold Coast (25)
- Golden Visa Programs (10)
- Historic Homes (8)
- Hogan Zavala Group (60)
- Holiday Abroad (1)
- International Citizenship (15)
- International Real Estate (31)
- Kitchen Design (13)
- Lakeview (14)
- Legacy (3)
- LGBTQ Housing (2)
- LGBTQ+ (4)
- Lifestyle (78)
- Lighting (2)
- Lincoln Park (14)
- Loft Living (5)
- Lofts (5)
- Logan Square (4)
- loneliness & aging (2)
- Loop (2)
- Luxury Market Index (4)
- Marina Towers (4)
- Market Insights (17)
- Market Update (36)
- Mid Century (2)
- New East Side (1)
- Outdoors (5)
- Pacaso Vacation Homes (3)
- pied-à-terre (15)
- Puerto Vallarta (8)
- Puerto Vallarta Real Estate (9)
- Real Estate Agents Success (11)
- Real Estate Industry (30)
- Real Estate Legal Changes (5)
- Real Estate Transactions (7)
- ritual (4)
- River North (21)
- River West (14)
- Second Homes (9)
- Seller Strategy (28)
- Selling and Buying in Chicago (34)
- Senior Housing (2)
- Streeterville (15)
- Summer (7)
- Sustainability (7)
- Taxes (5)
- Thanksgiving Travel (1)
- The 606 (1)
- The Henrys (1)
- Travel (1)
- Trends (29)
- Trifecta (17)
- Uptown (2)
- video (1)
- video for real estate (2)
- Wellness (9)
- West Loop (9)
- Wheaton (1)
- Wicker Park | Bucktown (4)
- Wines for Summer (2)
Recent Posts

Craig Hogan | Rudy Zavala